IneedMyVacation.com

🌀 Caribbean Hurricane Guarantee Hotels 2026: Refunds, Credits & Storm Rules

Fall can bring lower Caribbean resort prices, but a hurricane warning can put flights, deposits, and vacation days at risk. Caribbean hurricane guarantee hotels 2026 can lower that risk when a participating property offers refunds, credits, or rebooking after a defined storm trigger.

Affiliate Disclosure: This article contains affiliate links. If you book or purchase through these links, I Need My Vacation may earn a small commission at no extra cost to you. We only recommend services we genuinely trust and use ourselves to help you plan the perfect trip. Thank you for your support!

🌴 Compare Protected Caribbean Stays Before Rooms Disappear

A hotel guarantee is not travel insurance. Compare refundable rates, written storm policies, and the full trip total before a nonrefundable deposit locks you in.

💡 When the hotel page opens: Type “Grand Cayman” or “Grace Bay, Turks & Caicos,” set Sept–Nov dates, then filter “Free cancellation.”

💡 When the flight page opens: Enter your home airport + “GCM” (Grand Cayman) or “PLS” (Providenciales), then toggle “Flexible dates.”

🎯 Key Takeaways: Hurricane Guarantee Hotels 2026

  • 🌀 A hurricane guarantee only applies when the property’s written storm trigger is actually met.
  • 🇰🇾 Cayman offers a documented 2026 program across participating properties on Grand Cayman, Cayman Brac, and Little Cayman.
  • 🏨 Turks and Caicos policies differ by resort, booking channel, deadline, and storm type.
  • 💳 Refunds, credits, and replacement stays are three different benefits with very different limits.
  • 🛡️ Travel insurance fills the gaps for flights, medical care, evacuation, and trip interruption that hotel policies exclude.

🌀 What Protection Do Caribbean Hurricane Guarantee Hotels Actually Offer in 2026?

A hurricane guarantee is a promise from a hotel, villa, resort, or tourism program. It may offer a refund for unused nights, waived cancellation fees, a future-stay credit, or a replacement vacation after a storm. It is not automatic across every island — the exact booking terms control the result.

Destination / PropertyStorm TriggerMain BenefitKey Restriction
Cayman participating staysOfficial watch or warningRefund, credit, rebookingTerms vary by property
Ellipse Grace BayNHC alert + damage rulesRefunds / unused nightsTropical storms separate terms
Ports of Call ResortNHC alert near arrivalCancel or same-rate rescheduleEligible direct bookings only
Bermuda modelHurricane-force forecast testCancellation / replacement stayNot confirmed as a 2026 program

A named storm, rainy forecast, or flight anxiety does not automatically create a hotel claim.

Does the Cayman Islands Worry Free Hurricane Guarantee cover all three islands?

The Cayman Islands Department of Tourism has the strongest documented destination-wide program for 2026. The Worry Free Hurricane Guarantee applies to participating hotels, resorts, villas, condominiums, and other stays on Grand Cayman, Cayman Brac, and Little Cayman. The travel window runs from June 1 through November 30, 2026. An official hurricane watch or warning issued by the Cayman Islands Government or Hazard Management can activate protection — depending on the property, that may mean a refund for unused days, a 12-month credit, waived cancellation fees, limited penalties, or a replacement stay. Check Cayman’s 2026 hurricane guarantee details and confirm the written policy attached to your room before you pay.
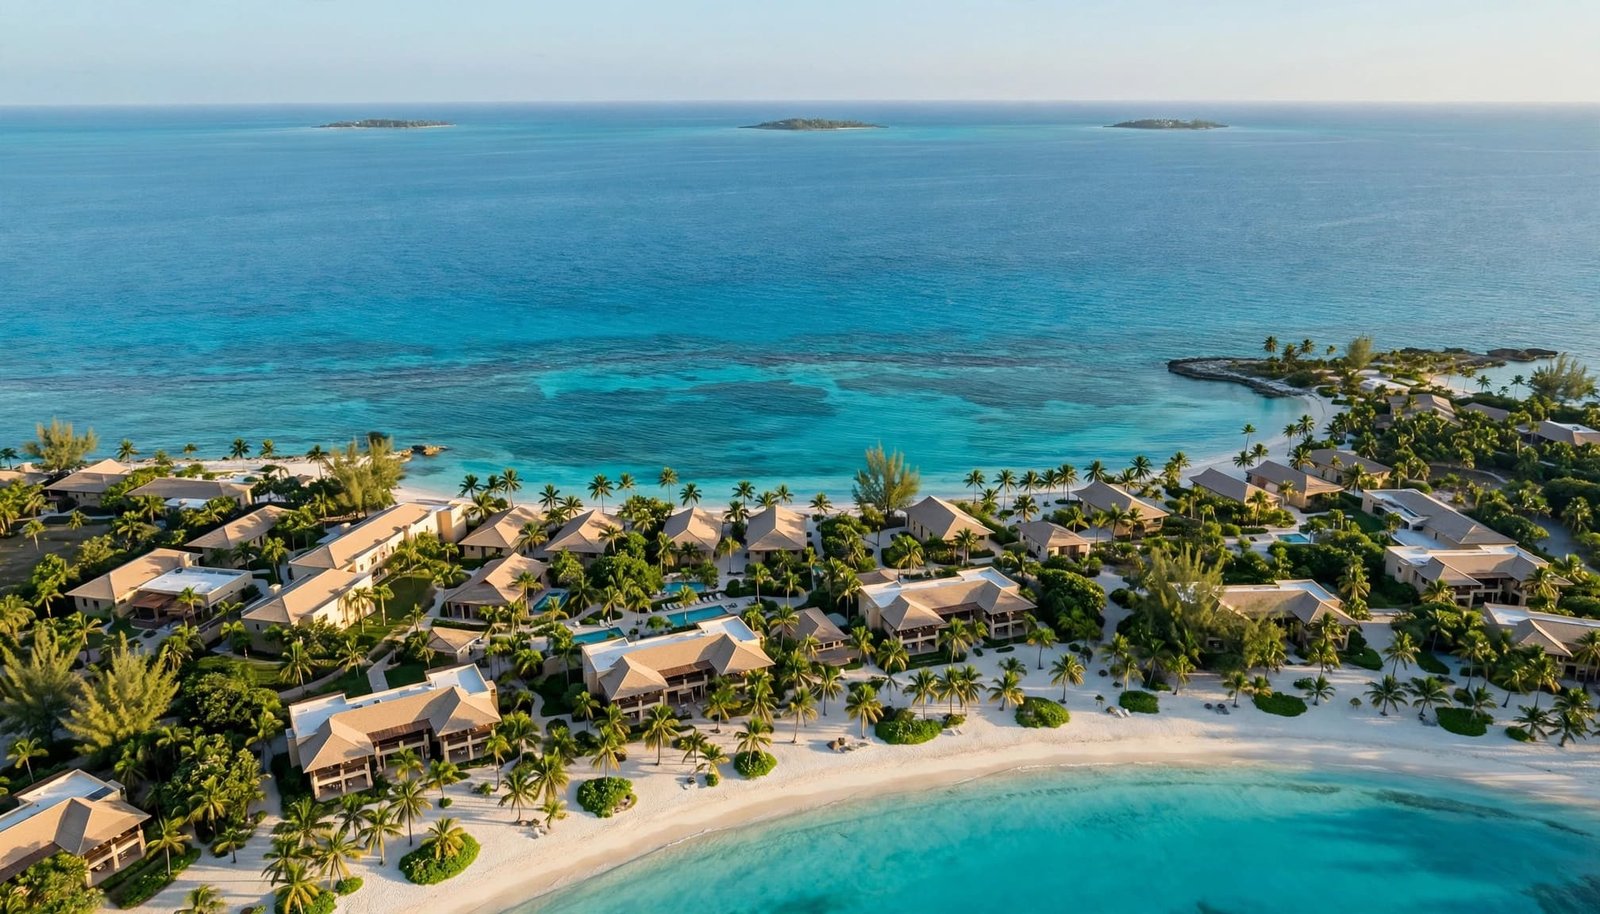
A beachfront resort with palm trees, white sand, turquoise water, and distant islands.

Why do Turks and Caicos policies show why the fine print matters?

Turks and Caicos has useful property-level examples, but don’t assume every Grace Bay resort has the same protection. Ellipse Grace Bay uses National Hurricane Center watch or warning language and a 72-hour uncertainty zone, and its policy treats hurricanes and tropical storms differently. Ports of Call Resort has different rules: eligible direct bookings must fall within a seven-day arrival window, and guests generally need to cancel at least 48 hours before arrival.
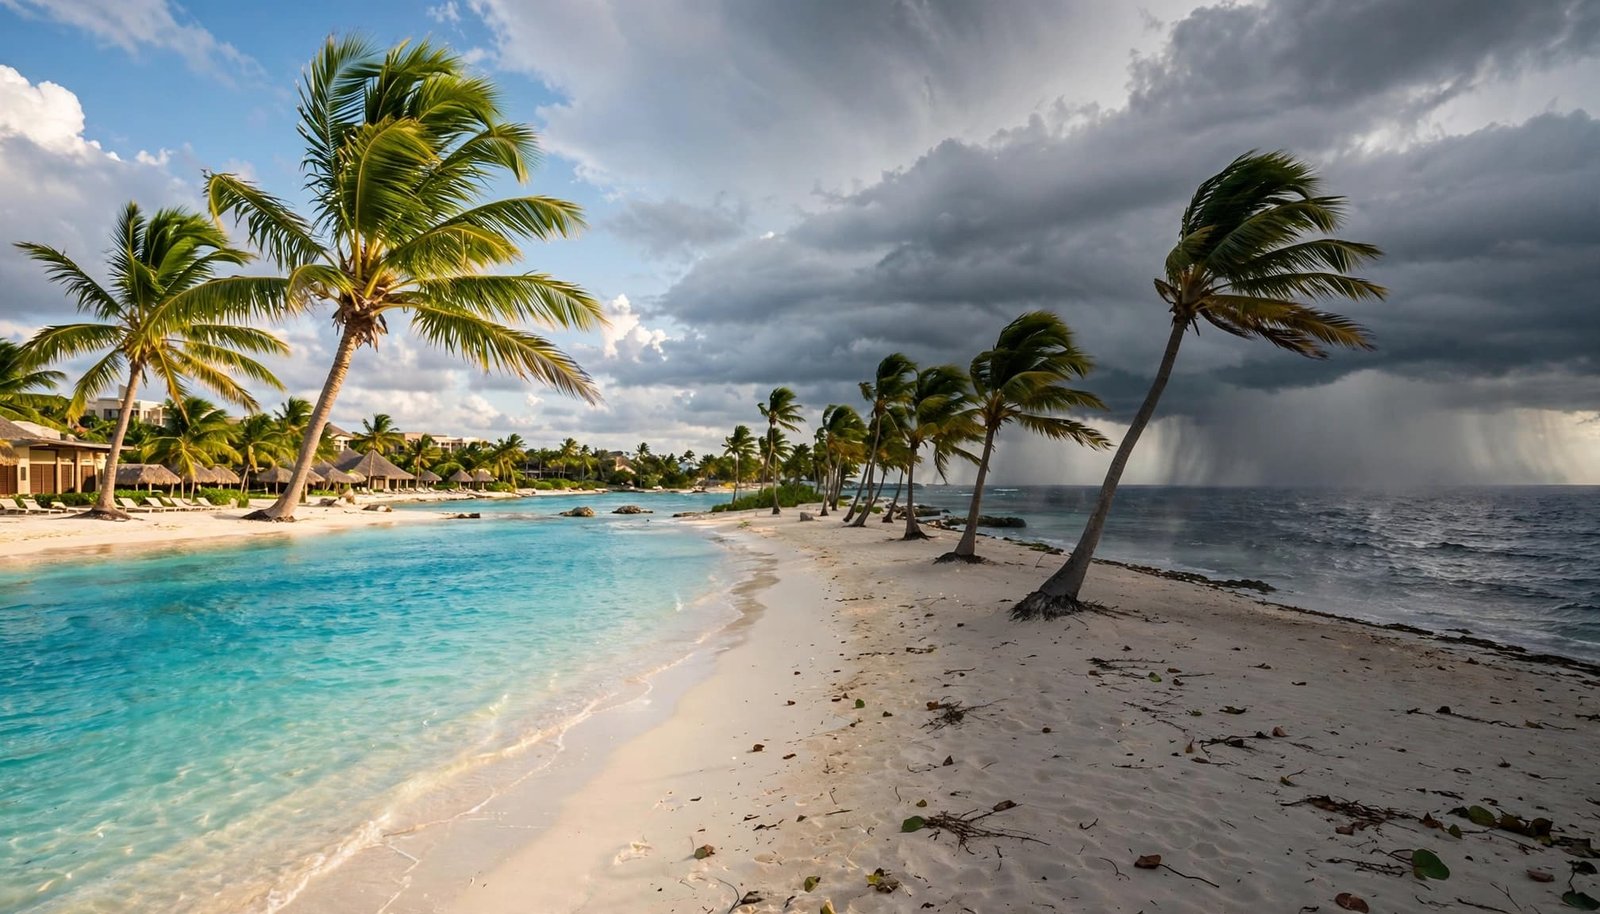
Empty Grace Bay beach with turquoise water, bending palms, and rain clouds offshore.

Is Bermuda’s hurricane guarantee a 2026 promise?

Bermuda has used a hurricane guarantee model that allowed penalty-free cancellation when a hurricane-force storm met a defined forecast-distance test, and some guests could receive a complimentary return stay after reopening. The available information is older, and sources differ on whether the trigger was three or five days before arrival. Treat it as an example, not a guaranteed 2026 benefit.

📄 How Do Island Hurricane Guarantees Protect Your Fall Vacation?

The best time to understand a guarantee is before you book. Save the policy PDF, booking confirmation, and cancellation terms in one folder. If weather changes, you will need proof of the official alert and your reservation details. I never rely on a phone screenshot alone — save the resort’s contact number, airline notice, receipts, and all email replies.
Blurred travel documents, passport, and pen beside a Caribbean map on a sunlit wooden table.

What storm conditions actually activate a hotel guarantee?

A hurricane watch means hurricane conditions are possible; a hurricane warning means they are expected. A tropical storm warning, mandatory evacuation, resort closure, or property damage may have different results. A forecast alone may not qualify, and a tropical storm can produce a credit or rescheduling option instead of a cash refund. Don’t cancel first and investigate later.

Are refunds, credits, and replacement stays the same benefit?

No. A refund returns qualifying unused money. A future-stay credit gives you another chance to travel but may expire within 12 months. A replacement stay can depend on reopening dates, blackout periods, availability, your original room type, and resort approval. Hotel guarantees also often cover room nights only — flights, transfers, excursions, tips, resort fees, and prepaid activities may sit outside the policy.

Why doesn’t hotel protection replace travel insurance?

A resort policy may protect the room, but travel insurance can cover other prepaid costs when a covered event interrupts your trip — flights, extra hotel nights, medical expenses, emergency evacuation, or trip interruption. When I compare plans, I look for emergency medical coverage around $100,000 and medical evacuation of $250,000 or more as a starting point. Many plans offer pre-existing-condition waivers only when purchased soon after the first trip payment, commonly within 14 to 21 days.

🛡️ Compare Travel Protection While Early Benefits Last

Hurricane-related coverage usually must be purchased before a storm is named. Buy early, then keep every policy document in one folder.

🛡️ Compare Caribbean Travel Protection

💡 When the page opens: Enter your trip cost, dates, and traveler ages, then confirm “hurricane/weather” and “trip interruption” coverage before checkout.

🏨 How Do You Choose a Protected Caribbean Resort for Fall 2026?

The Atlantic hurricane season runs from June 1 through November 30. Late summer and fall can bring strong resort deals, especially September and October. The trade-off is clear: lower room prices can disappear fast if the booking is rigid. Start with your island, dates, and full nonrefundable trip value, then compare the property guarantee, direct-booking requirement, refundable rate, and travel insurance gaps.

🏨 2026 Fall Stay Snapshot (from ~ per night): Kimpton Seafire Resort (Grand Cayman) ~$450; Margaritaville Beach Resort Grand Cayman ~$380; Ellipse Grace Bay (Turks & Caicos) ~$700; Ports of Call Resort (Grace Bay) ~$250; Grace Bay Club ~$900; Hamilton Princess (Bermuda) ~$500.

✈️ Fall 2026 Airfare Snapshot (round-trip economy, from ~): American MIA–GCM ~$340; JetBlue JFK–GCM ~$380; American MIA–PLS ~$390; JetBlue BOS–PLS ~$410; Delta ATL–GCM ~$420. September–October shoulder dates usually price lowest.

✅ Pros: Fall rates can be lower than winter high season; flexible reservations protect changing plans; participating properties may offer real weather-related relief.

❌ Cons: Storm policies are not identical; cheap rates may be fully nonrefundable; flight and medical costs often need separate protection.

What five questions should you ask before paying the resort deposit?

  1. What agency issues the official alert, and does the policy cover a watch, warning, tropical storm, evacuation, or closure?
  2. Must I book direct, or does my online travel agency reservation qualify?
  3. Will I receive cash, a credit, or a replacement stay if a storm affects my trip?
  4. Are flights, meals, transfers, excursions, taxes, and resort fees included?
  5. What are the cancellation deadline, one-night penalty, blackout dates, reopening rules, and rate-change limits?

Ask for the answer in writing. A friendly phone promise is not the same as a booking term. For more timing help, review these cheapest Caribbean travel deals before picking the lowest nightly rate.

How do you build a fall backup plan instead of relying on one promise?

Build layers around your trip: use flexible lodging when the price difference makes sense, choose flight times that leave room for disruption, and keep travel insurance, emergency savings, and policy files easy to reach. A local eSIM can help if resort Wi-Fi becomes unreliable and you need to reach an airline, hotel, or assistance team. Check official National Hurricane Center and local government updates, not only social media posts.
A traveler sits by a resort window, holding a phone while looking toward the ocean.

📱 Stay Reachable If Resort Wi-Fi Fails During a Storm

An eSIM keeps you connected to airline alerts, hotel updates, and assistance teams even when property internet goes down.

📱 Get a Caribbean eSIM

💡 When the page opens: Select the “Caribbean & Latin America” regional eSIM so one plan covers Cayman, TCI, and backup islands.

🔋 Storm-Season Essential: Backup Power for Your Trip

Jackery Explorer 1000 v2 Portable Power Station (~$499)

Hurricane-season stays can mean brief power flickers or Wi-Fi outages. The Jackery Explorer 1000 v2 keeps phones, CPAP machines, laptops, and Wi-Fi hotspots charged through an outage, so you never lose contact with your airline, resort, or insurance team when a storm trigger is announced.

✅ 1070Wh Capacity ✅ UPS-Grade Home Backup ✅ Airline-Safe LiFePO4 Battery
🛒 Check Jackery Explorer 1000 v2 Pricing

💡 When Amazon opens: Copy/paste “Jackery Explorer 1000 v2” to compare the standalone unit vs. solar bundle pricing.

❓ People Also Ask: Hurricane Guarantee FAQ

1. Which Caribbean islands have hurricane guarantees?

The Cayman Islands has a documented destination-wide 2026 Worry Free Hurricane Guarantee for participating properties on Grand Cayman, Cayman Brac, and Little Cayman. Turks and Caicos has property-specific examples like Ellipse Grace Bay and Ports of Call Resort. Other islands and hotels may have separate policies, so check each booking individually.

2. What happens if a tropical storm cancels your Caribbean resort stay?

It depends on the policy wording. You may receive waived fees, a future-stay credit, a refund for unused nights, rescheduling, or no benefit if the guarantee covers hurricanes only. Document the official warning and contact your booking source before you cancel.

3. Do hurricane guarantees cover canceled flights?

Most hotel guarantees focus on lodging only. They may not reimburse airfare, airport transfers, excursions, or extra hotel nights. Airline rules, travel insurance, and applicable passenger protections are more likely to address a canceled flight.

🌅 How Do You Plan a Fall Escape With Protection Built In?

A hurricane guarantee can make a fall Caribbean stay feel less risky, but only when you understand the trigger, deadline, booking channel, and payout type. A written property policy is a good start; flexible reservations and separate travel insurance protect the bigger costs around it. You can also compare vacation bookings and travel deals before prices move.
Empty Caribbean beach with turquoise water, green palms, and sunlight breaking through clouds.

🏨 Compare Protected Resort Options Before Windows Close

Lock a flexible rate now, then layer a written storm policy and travel insurance on top before the best fall rooms disappear.

💡 When the page opens: Type “Grand Cayman” or “Grace Bay” + Sept–Oct dates, then filter “Free cancellation” and read the storm policy link.

Support the Blog

If you love our travel guides and vacation tips, consider buying us a coffee to fuel the next adventure!

Buy Me a Coffee

© 2026 I Need My Vacation. All rights reserved.
This article contains affiliate links. If you book through these links, I Need My Vacation may earn a commission at no extra cost to you. We only recommend services we trust and use ourselves.

🛡️ Caribbean Travel Insurance: The Ultimate 2026 Guide for All-Inclusive Resorts

Caribbean travel insurance reimburses prepaid, nonrefundable resort and flight costs when a covered problem stops your trip. It also pays for emergency medical care, evacuation, and delays, but it does not replace regular health insurance. Buy early to unlock time-sensitive waivers and hurricane protection.

An all-inclusive vacation can look simple on paper. Resort, meals, drinks, airport transfer, beach time. Then a flight is canceled, a child gets sick, or a hurricane changes the whole plan. The money tied up in a Caribbean trip can add up fast. Buy coverage when you make your first nonrefundable payment, not when bad weather is already on the radar.

🎯 Key Takeaways Before You Buy

  • 💰 Insure the full prepaid trip cost. Include the resort package, flights, airport transfers, excursions, and extra hotel nights that cannot be refunded.
  • 🚑 Emergency medical coverage matters most. Your regular medical insurance may offer limited protection overseas. A plan with at least $100,000 in emergency medical benefits is a safer starting point.
  • 🚁 Choose $250,000 or more for medical evacuation. Island care can be excellent, but serious cases may require air transport to another island or back home.
  • Buy early for pre-existing condition waivers and CFAR. Many policies require purchase within 14 to 15 days of your first trip deposit.
  • 🌀 Hurricanes are covered only under certain conditions. You usually need to buy the policy before a storm is named or otherwise foreseeable.

🌴 Protect Your Vacation Before Prices Go Up

Compare medical, evacuation, and cancellation benefits in a travel protection program while early-purchase benefits may still be available.

📍 Table of Contents

📋 What Does Caribbean Travel Insurance Cover on an All-Inclusive Vacation?

A comprehensive plan, sometimes called a travel protection program, protects the prepaid and nonrefundable parts of your trip. For an all-inclusive vacation, that may be more than the resort confirmation. It can include flights, a private transfer, a pre-booked catamaran trip, and the hotel night near the airport before your flight home.

Trip cancellation reimburses eligible costs if a covered reason forces you to cancel before departure. Common reasons include serious illness, injury, death in the family, certain job losses, jury duty, or severe weather. Supplier failure, including financial default, qualifies only when the plan specifically lists it.

🛡️ Benefit✅ What it may pay for❌ What not to assume
Trip cancellationNonrefundable prepaid arrangements for a covered reason before departureA refund because you changed your mind
Trip interruptionUnused arrangements and eligible extra transport homeEvery expense after leaving early
Travel delayMeals, lodging, and local transport after a qualifying delayReimbursement for a short airport wait
Missed connectionAdded transport and lodging when a covered delay causes a missed departureA new ticket if you arrived late yourself

An all-inclusive booking creates one common mistake. Travelers insure only the resort deposit, then forget the separate flight, airport hotel, or excursion. I use one rule: if I would be upset to lose that prepaid money, I add it to the trip cost.

🚑 Why Do Medical Insurance and Evacuation Matter Most?

A resort doctor visit or a clinic prescription may be manageable, even if your home medical insurance does not apply abroad. A heart issue, serious infection, diving injury, or car accident is different. Island hospitals may stabilize you, but advanced treatment could be on another island or in the United States.

⚠️ Warning: The State Department warns that U.S. health coverage (including Medicare) rarely pays outside the country. Look for at least $100,000 in emergency medical coverage and $250,000 for medical evacuation to ensure you aren’t left with a massive air-transport bill.

Emergency medical evacuation is separate. It pays for medically necessary transportation to the nearest appropriate facility, or sometimes home, when local care is not enough. Air transport costs can be huge. A $50,000 evacuation limit may disappear faster than people expect. For remote islands, travel with children, or pregnancy concerns, $500,000 is more comfortable.

Call the insurer’s 24-hour assistance number before arranging an evacuation whenever possible. Many policies require the assistance team to approve and coordinate medical evacuation.

Does primary coverage or secondary insurance matter?

Yes. Primary travel medical insurance pays eligible claims first, without waiting for your home health insurer to deny the claim. It means less paperwork while you are dealing with a medical emergency. Secondary insurance pays after other insurance, meaning you could need to submit the claim to your home plan first.

🌀 How Do Hurricanes and “Cancel For Any Reason” Work?

The Atlantic hurricane season runs from June 1 through November 30. It also overlaps with some of the cheapest resort rates. That lower price can be tempting, but I never book hurricane-season travel without reading the weather terms in my travel insurance. If you are booking during the lower-priced months, compare the weather risk with your savings. Our guide to cheapest Caribbean travel deals can help you weigh lower resort prices against a more flexible travel plan.

Trip cancellation can apply if a hurricane forces your resort to close, your destination airport shuts down, or your home becomes uninhabitable. The big catch is timing. Once a storm is named, it becomes a known event. Buying a new plan after that point will not cover losses caused by that storm.

Is Cancel For Any Reason (CFAR) worth it?

Cancel for any reason (CFAR) is an optional upgrade. It lets you cancel for a reason not listed in the standard plan, such as a breakup, lost interest, or simply not wanting to travel. CFAR offers partial reimbursement (usually 50% to 75%), not a full refund. You must buy within a short window after the first deposit and cancel at least 48 hours before departure.

🚫 What Does Travel Insurance Usually Not Cover?

The policy is a safety net, not a blank check. Your medical insurance at home does not make an excluded activity or elective treatment payable under this plan. Read the insurance policy before you pay, especially if your vacation includes water activities or late nights at the resort.

💡 Pro Tip: Snorkeling from the beach may be covered under one plan, while another treats it differently. Scuba diving is even more policy-dependent. If a resort sells an activity, that does not mean your plan covers it. Check the policy’s exclusions before booking.

Most standard policies will not reimburse you for canceling because you are worried about weather while your resort and flights are still operating, injuries connected to intoxication, adventure activities excluded by the plan (like parasailing or cliff jumping), or lost belongings left unattended beside a pool.

📝 How Can You Choose Caribbean Travel Insurance Without Overpaying?

Start with your actual trip value. Add every nonrefundable cost for every traveler. Do not include refundable payments you can recover without making a claim. This keeps you from both underinsuring and paying extra for coverage you do not need.

📊 Coverage Area🎯 Solid Starting Point💡 Why it matters
Medical treatment abroad$100,000 or moreOverseas care is expensive and home plans rarely pay
Medical evacuation$250,000 or moreSerious cases may require air transport off the island
Cancellation benefitFull nonrefundable trip costProtects your prepaid bookings before departure
Interruption benefitAt least 150% of insured amountExtra transportation home can cost more than expected

Why should you buy early if you have pre-existing medical conditions?

A waiver for pre-existing medical conditions can cover medical issues that would otherwise be excluded. The deadline is often 14 to 15 days after your first trip deposit. This is one reason I buy a policy on the same day I make the first major payment. For a closer look at the fine print, use this guide to booking a policy that actually covers you.

📱 Stay Connected During Emergencies

If you need to call your insurance assistance team or rebook flights, resort Wi-Fi isn’t always reliable. Get an eSIM so you have data the moment you land.

📶 Get a Caribbean eSIM

❓ People Also Ask: Caribbean Travel Insurance FAQ

1. Does Caribbean travel insurance cover medical expenses outside the US?

Yes, if your plan includes emergency medical coverage. It can pay eligible costs for illness or injury during your trip, subject to deductibles and maximums. Confirm that the plan includes medical evacuation before you leave, as domestic health insurance rarely covers overseas care.

2. Will travel insurance cover a hurricane in the Caribbean?

It may cover cancellation, interruption, or delays when a hurricane closes your resort, airport, or route. However, you must buy coverage before the storm becomes a named, known event. A plan will not pay simply because you no longer feel comfortable traveling due to a forecast.

3. Does travel insurance cover all-inclusive resort activities?

Not always. Swimming and casual snorkeling may be included, but scuba diving, parasailing, jet skis, zip lines, and ATV excursions often have exclusions. Always check the plan’s hazardous sports list before booking the activity.

🎉 Book the Resort, But Protect the Money

The best plan protects the expensive parts of your vacation, not only your suitcase. Prioritize medical benefits, evacuation limits, cancellation protection, and early-purchase rules over a low premium. A beautiful all-inclusive resort is still worth protecting when flights, excursions, and family plans are on the line.

🛡️ Secure Your Peace of Mind Today

Compare comprehensive travel insurance before your next Caribbean deposit becomes non-refundable.

© 2026 I Need My Vacation. All rights reserved.

Support the Blog

If you love the travel tips and content, consider buying me a coffee or fueling my next adventure!

Support via Cash App

This article contains affiliate links. If you book through these links, I Need My Vacation may earn a commission at no extra cost to you. We only recommend services we trust and use ourselves.

🛡️ Is Caribbean Cruise Travel Insurance Worth It? (2026 Guide)

Yes, Caribbean cruise travel insurance is worth buying for most travelers when the trip is prepaid, flights are separate, or your health plan lacks strong international coverage. You can skip comprehensive coverage only when you can afford to lose every nonrefundable dollar and already carry strong medical and evacuation protection.

A Caribbean sailing can look simple on booking day. Then a delayed flight, a sick child, a hurricane watch, or a missed embarkation turns a dream week in turquoise water into a costly mess. That is where Caribbean cruise travel insurance provides essential vacation protection.

🎯 Key Takeaways

  • 💰 Comprehensive travel insurance is worth it when your cruise, separate flights, hotels, and excursions are mostly nonrefundable.
  • 🚑 Emergency medical and evacuation limits matter most because a medical emergency or island hospital transfer can quickly become extremely costly.
  • ⚖️ Compare cruise line plans with independent policies to ensure separate bookings like flights and hotels are fully protected.
  • Buy early to unlock time-sensitive benefits, including pre-existing condition waivers and Cancel For Any Reason upgrade options.

🌴 Protect Your Trip Before Prices Go Up

Compare cruise medical, cancellation, and evacuation benefits before your final payment date to lock in the best rates.

📍 Table of Contents

⚓ When Do You Need Caribbean Cruise Travel Insurance?

You don’t need insurance just because you are taking a cruise. You need it when losing the trip money would hurt, or when getting home after a medical emergency would be difficult.

For many travelers, a Caribbean cruise includes more than the cabin. You may have a flight to Miami, a hotel near Port Canaveral, airport parking, a private transfer, and prepaid excursions at your next port of call in St. Thomas or Cozumel. Miss the ship because your flight is late, and those separate bookings can pile up fast.

This is why I tell families and couples to count the non-refundable trip cost before choosing a policy. A $1,200 cruise can become a $3,500 vacation once flights and extras are added. Our guide to the hidden costs of cruising is a good reminder that the advertised fare rarely tells the full story.

A cruise ship railing overlooking a turquoise sea and lush island.

✅ Travel insurance is usually a smart buy when:
• You are flying in on embarkation day.
• The cruise is a big anniversary, family reunion, or honeymoon.
• A traveler has a medical condition that could cause a last-minute cancellation.
• You paid for a suite, premium excursions, or expensive island stays.
• You are cruising during a weather-sensitive period.

A budget cruiser may decide to self-insure a low-cost, refundable sailing. That can work. But be honest about the worst-case number. Could you comfortably pay for replacement flights, a hotel, medical care, and transportation home? If the answer is no, insurance is not an extra. It is part of the trip budget.

📋 What Does Caribbean Cruise Travel Insurance Actually Cover?

Most comprehensive policies bundle several benefits together. The names can look similar, but the dollar limits and rules can be very different.

The policy should cover the financial side of a canceled trip, but it also needs to help when you are sick at sea or in port. A ship’s medical center is convenient, yet it is not a replacement for a hospital. Medical transport between islands can add another layer of cost.

Close-up view of lifeboats on a cruise ship, highlighting safety equipment.

Photo by Diego F. Parra

Trip cancellation protects prepaid expenses

Trip cancellation protection reimburses eligible prepaid, nonrefundable costs when you cancel for a covered reason. Serious illness, injury, certain family emergencies, and some weather events are common examples. The exact list belongs in the policy certificate.

This is where travelers get caught. Changing your mind, worrying about rain, or deciding the timing is bad usually does not qualify. Cancel For Any Reason coverage can offer more flexibility, but it costs more and still has deadlines and reimbursement limits.

If you book late, don’t assume you missed your chance. Our last-minute travel insurance guide explains why buying quickly still matters, especially for benefits with strict purchase windows.

Emergency medical and evacuation coverage matter most

Emergency medical coverage can help with eligible treatment when you get sick or injured during your trip. Medical evacuation coverage can help move you to an appropriate hospital, or arrange a ship-to-shore evacuation when medically necessary.

⚠️ Warning: A policy’s dollar limit matters more than its headline price when the nearest hospital requires a boat, an ambulance, or an air transfer.

Review your current health plan before you sail. Do not assume it pays outside the United States, on a ship, or in a foreign port. Medicare coverage is also not the same as worldwide private medical coverage.

⚖️ Is Cruise Line Insurance Better Than Independent Coverage?

Buying cruise line insurance offers protection during checkout because it is easy. One click, one payment, and you are done. That convenience can be worth it for some travelers.

But I would never buy it without a quick comparison. Cruise line plans may have different reimbursement methods, such as paying out in future cruise credits rather than a cash refund, lower medical limits, or rules that work better for the cruise fare than for your separately booked flights and hotel.

📊 Feature to Compare🚢 Cruise Line Plan🛡️ Independent Plan
Buying processFast during checkoutTakes a few minutes to compare
Cruise fare protectionOften includedIncluded if you insure the amount
Flights and hotelMay be limitedCan include separate expenses
Medical & evacuation limitsVary by cruise lineEasier to shop by limit

The best option is the one that protects your actual booking. If your airfare was booked with points or miles, read the policy language. If your hotel has free cancellation, you may not need to insure that part. Do not insure refundable expenses simply because they are expensive.

For first-time cruisers, the ship itself can be confusing enough. Read our guide to the best Caribbean cruise lines before you choose a route, then match coverage to the line, ports, season, and travel style.

💰 How Much Does Caribbean Cruise Insurance Cost?

The price depends on your age, trip cost, trip length, destination, and the benefits you choose. A comprehensive travel insurance policy often costs around 4% to 10% of prepaid trip expenses, according to industry comparison data.

For a Caribbean trip, the average insurance cost is about $250 to $350. That does not mean every traveler will pay that amount. A younger couple insuring a modest cruise may find a lower price. A multigenerational family in suites can see a much higher quote.

🧳 Your Travel Situation🛡️ Coverage Worth Considering
Low-cost, refundable cruiseEmergency medical & evacuation coverage
Cruise plus non-refundable flightsComprehensive policy with delay & missed connection
Family cruise with several cabinsComprehensive plan for each traveler
Traveler with pre-existing conditionsPolicy with a pre-existing condition waiver, if eligible

📝 How Do You Pick a Policy Without Overpaying?

Start with your total prepaid, nonrefundable costs. Include the cruise, airfare, hotel before the ship, transfers, and excursions that cannot be refunded. Leave out costs you can cancel for free.

Next, compare these details before paying:

  1. Check the emergency medical coverage and medical evacuation coverage limits, then look at whether the policy is primary or secondary.
  2. Read the list of covered cancellation and interruption reasons, and verify that the provider offers reliable 24/7 emergency travel assistance.
  3. Look for the purchase deadline for pre-existing medical conditions waivers or optional Cancel For Any Reason upgrades.
  4. Confirm that your trip dates include the flight out, cruise dates, post-cruise stay, and return flight.
  5. Save the policy certificate, emergency assistance number, booking receipts, and airline notices in one phone folder.

🌺 Sail With a Backup Plan

Get the policy details in writing before your cruise payment becomes nonrefundable.

❓ People Also Ask: Caribbean Cruise Insurance FAQ

1. Does Caribbean cruise travel insurance cover hurricanes?

It can cover a hurricane-related cancellation, delay, or trip interruption when the event meets the policy’s rules. A named storm alone may not trigger benefits. Read the weather language and buy before a storm is foreseeable, because insurance does not cover known events.

2. Does travel insurance cover a missed cruise because of a delayed flight?

It may, if the flight delay is a covered reason and lasts long enough under the plan. Travel delay and missed connection coverage can help with catch-up transportation, lodging, or unused trip costs. Flying in one day early still gives you more control than hoping a same-day flight runs perfectly.

3. Is cruise line insurance enough for a Caribbean cruise?

Sometimes, but not automatically. Compare cruise line insurance vs. third-party travel insurance regarding emergency medical, evacuation, flight delay, and cancellation rules. An outside plan may better protect separately booked flights, hotels, and excursions.

🎉 Make the Insurance Decision Before You Sail

A Caribbean cruise should feel like warm water, island music, and slow mornings on the balcony. It should not feel like a financial gamble because one flight, illness, or storm changed the plan.

Caribbean cruise travel insurance is most valuable when it protects the full vacation, not only the cabin. Compare the medical and evacuation limits, insure the nonrefundable costs, and buy before deadlines close.

🎒 Pack Smart for Your Caribbean Escape

Don’t get caught without the essentials. Get resort-casual wear, reef-safe sunscreen, and travel adapters delivered fast.

🛒 Shop Travel Essentials

© 2026 I Need My Vacation. All rights reserved.

Support the Blog

If you love the travel tips and content, consider buying me a coffee or fueling my next adventure!

Support via Cash App

Pin It on Pinterest